• Market Cap: $2,418,160,157,835.35
  • 24h Vol: $108,433,118,919.67
  • BTC Dominance: 56.67%
XBT.Market
Advertisement
  • Home
  • Coins MarketCap
  • Crypto Exchanges
  • Crypto Calculator
  • Top Gainers and Loser
  • News
  • Contact Us
No Result
View All Result
XBT.Market
No Result
View All Result
Home Bitcoin

The legal dangers of getting involved with DAOs

Jon Hartney by Jon Hartney
January 26, 2023
in Bitcoin, Blockchain, Business, Market
0

QNT whales have started securing profits after the token's 450%-plus price rally since June 2022

189
SHARES
1.5k
VIEWS
Share on FacebookShare on Twitter

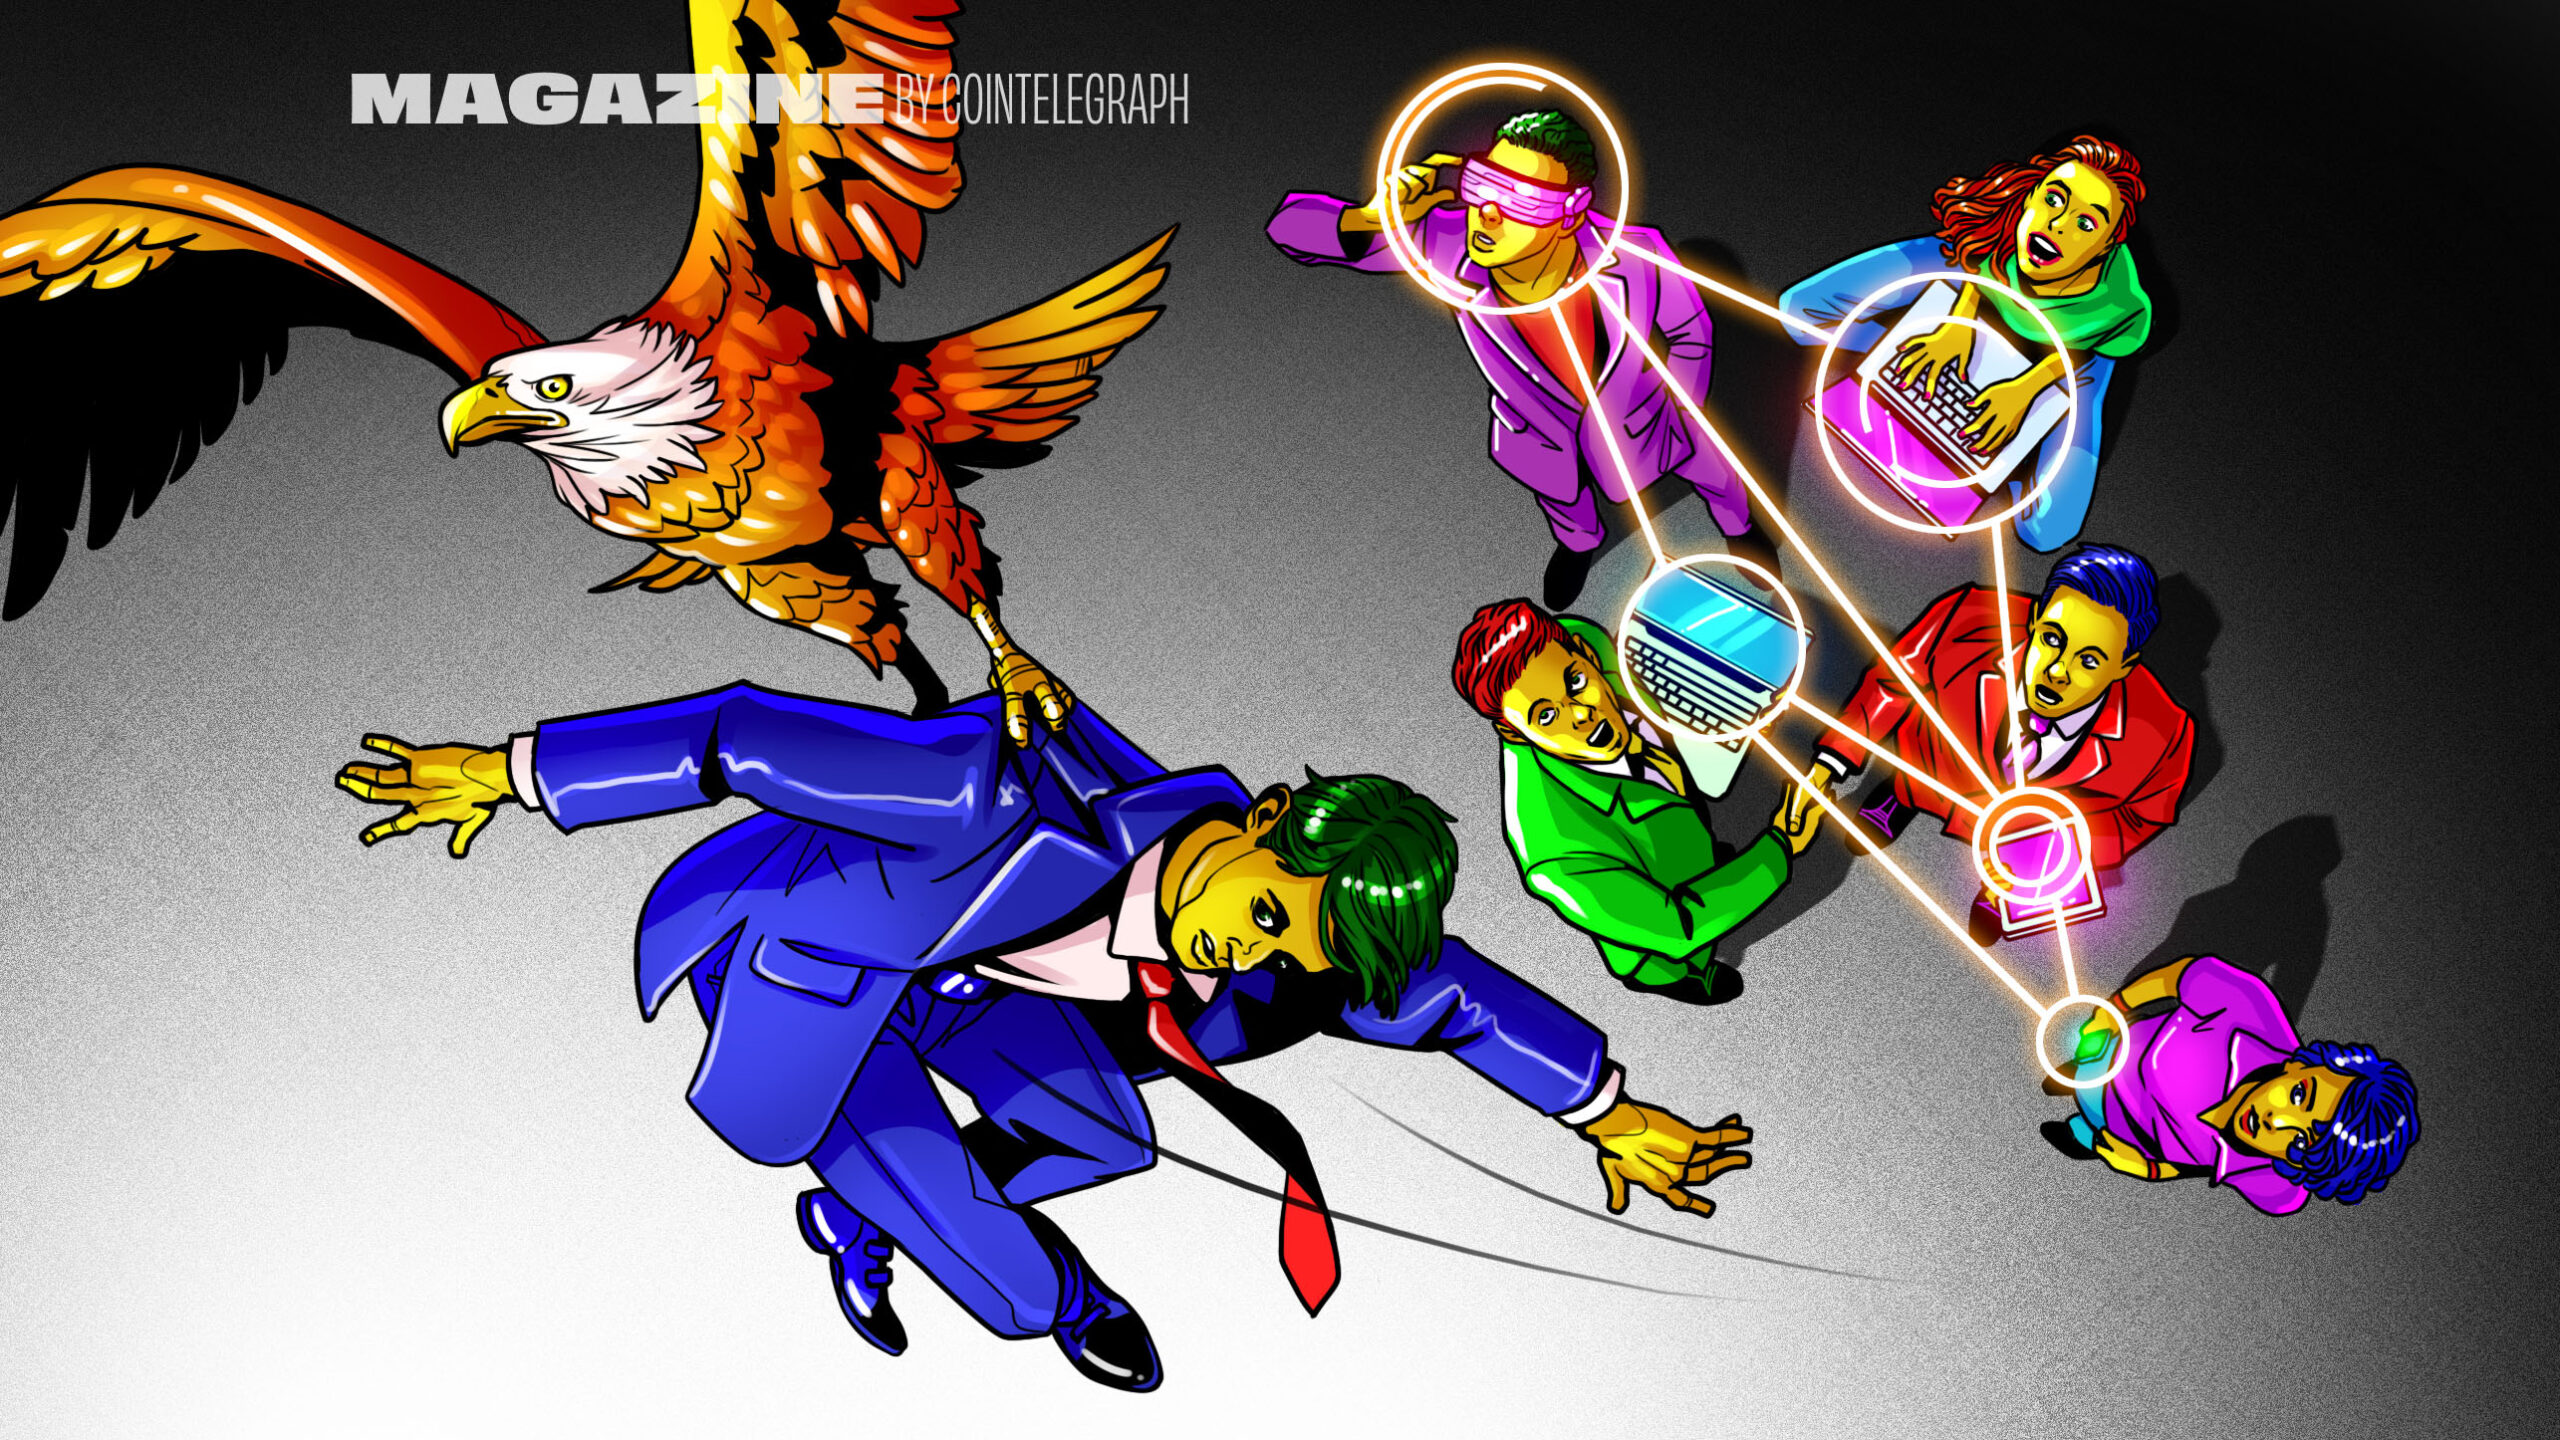
Buying DAO tokens? That’s no longer risk-free: Courts might consider you a partner in the business and judge you liable for millions in hacked funds. Another legal trap may be found simply working for a DAO — and implementing community decisions that turn out to be illegal in some far-flung jurisdiction. With many DAO communities […]

Buying DAO tokens? Thats no longer risk-free: Courts might consider you a partner in the business and judge you liable for millions in hacked funds. Another legal trap may be found simply working for a DAO and implementing community decisions that turn out to be illegal in some far-flung jurisdiction.

With many DAO communities waking up to the reality that they need some sort of legal structure or legal personality in order to act in the real world, solutions from mimicking corporate structures to anonymously run foundations are being floated by lawyers around the world.

Nothing in this article should be construed as legal advice and not just because the law isnt clear about any of it.

Code is law?

In 2021, Magazine interviewed Griff Green, whose heroic actions to thwart The DAO hack on the morning of June 17, 2016, helped save a good proportion of the 14% of Ether in existence at the time. By identifying how the exploit worked, his team of hackers worked to steal faster than the malicious actor, thus limiting the amount taken by the individual who discovered the error in The DAOs code. But who did this ETH belong to? 

Did it belong to the 11,000 investors who had contributed Ether toward the project in the previous month? If so, what claim did they have, considering that these investors had handed their money to an organization without leaders or jurisdiction, governed entirely by smart contracts that operated according to the votes of investors?

Or did it belong to the malicious hacker who simply interacted with the publicly available smart contract in a way that allowed them to withdraw Ether? Many would argue this is perfectly legal as per the code is law mantra.

Since The DAO had no legal personality, by what law could it hope to pursue the hacker, even if they were identified? The same goes for the investors how could they claim that the stolen Ether was theirs, given they made no legal agreements and signed no contracts when making their investments?

Perhaps the Ether that Greens team got a hold of was now rightfully theirs? Green acknowledges that he took a huge risk with the preemptive stealing of 10% of the Ether in circulation and recalls how as word spread, a multitude of legal threats poured in demanding how the recovered funds should be distributed despite the fact that we were just normal people; we didnt have a company. Eventually, Greens team returned the funds through a decentralized application.

After finding Ooki DAO had capacity to be sued and served by the @CFTC, Court enters default judgment against Ooki DAO when it fails to answer. It will be interesting to see if this gets challenged and what issues will arise when the CFTC seeks to enforce its judgment. pic.twitter.com/7NsW3AHVkZ

— Alex More (@UTAMore) January 18, 2023

These questions are just now beginning to be tested, with one of the first (developing) cases to emerge being that of Ooki DAO, accused of breaking the Commodity Exchange Act (CEA) by allowing users to engage in retail commodity derivative trading transactions without registering the platform or conducting KYC procedures. In January 2023, the judge found Ooki to be an unincorporated association comprised of Token Holders, which could be sued in the same way as a person or corporation and that it could be served by posting a notice onto the DAOs online community forum.

Another recent example of pitting code against law can be found in the case of Avraham Eisenberg, who in December 2022 was arrested on the request of U.S. authorities in Puerto Rico for having run a highly profitable trading strategy that effectively exploited the smart contract of Mango Markets, a decentralized finance DAO draining it of $110 million.

He claimed the whole exploit was perfectly legal under the code is law mantra, but the FBI disagreed. The case is yet to be tested in court.

Partnerships, foundations or corporate wrappers?

When it comes to DAOs, The DAO can be understood as the original example upon which the concept is based. As such, The DAO is often considered an ideal example of what a decentralized autonomous organization is supposed to be: cryptographically decentralized with no real-world anchor, its operations automated by way of smart contracts, and organized by way of blockchain governance.

In practice, however, courts may interpret DAO structures as General Partnerships, which have unlimited joint and several liability for all participants, observes Jason Corbett, managing partner of blockchain-specialized boutique law firm Silk Legal. 

Jonathan Turnham, a partner at Cayman Islands law firm Travers Thorp Alberga, spends 95% of his time working on crypto law and agrees that its complicated. He explains that, in theory, a truly decentralized DAO that functions as a decentralized exchange or metaverse project can be a code-based business, a bunch of 1s and 0s and does not technically have a need for a real-world corporate structure or physical business. 

If a DAO envisions that it might ever need to sign any type of contract, it is not code-based and by some definitions not a DAO at all
If a DAO envisions that it might ever need to sign any type of contract, it is not code-based and, by some definitions, not a DAO at all. Source: Pexels

But in his experience of advising dozens of DAOs, this model of total decentralization tends to run into trouble quickly perhaps even in the first 10 minutes of operation. 

A codebase business still needs a front end, Turnham explains, listing real-world needs like domain names, web hosting, banking services or hiring lawyers all of which are very difficult to acquire and pay for as a non-registered ghost-like entity. Any DAO that needs to enter into contracts involving real estate, intellectual property or even buying the U.S. Constitution cannot simply be code-based, as they will need some type of legal personality. 

Youve got this awkward inability to bridge into the real world you know, right down to you just needing a damn credit card or bank account to be able to pay a non-crypto service provider.

Currently, DAOs have no legal status in most jurisdictions, says Irina Heaver, partner of Keystone Law, which specializes in the blockchain industry, and general partner of VC investment firm Ikigai Ventures. Shes talking in the context of metaverse projects that are being launched on decentralized protocols. Legally speaking, traditional companies seem to remain the main game in town.

A year ago crypto twitter raised $47million in days to buy a *copy* of the United States constitution.

Now we have Genesis, one of the largest crypto trading/lending desks, in need of $500 million.

Feel like this one is much more important.

Can someone spin up a DAO & save us?

— Luke Martin (@VentureCoinist) November 21, 2022

There are of course exceptions. The U.S. state of Wyoming has recognized American CryptoFed DAO as a legal entity, and Vermont has seemingly done so as well with dOrg LLC.

Oliver Goodenough, special counsel to the DAOs law firm Gravel & Shea, commented, We believe that dOrg is now the first legal entity that directly references blockchain code as its source of governance. Its material operations and ownership interests are managed entirely on-chain. A Senate committee report even recommended the Australian government should soon recognize DAOs in a legal capacity, though it is yet to act on the advice.

Read also
Features

Are CBDCs kryptonite for crypto?

Features

Sexual Violence in India: Blockchains Role in Empowering Survivors

Does legalizing DAOs kill what makes them special?

But Sarah E. Paul, partner at Eversheds Sutherlands, is critical of the way in which the legalization of DAOs has rolled out, pointing out that certain provisions of Wyomings DAO law are antithetical to the basic idea that a DAO is supposed to operate entirely via smart contracts.

DAOs would have to define in the articles of organization how the members will manage the DAO, including the extent to which governance would occur algorithmically theyre supposed to define how dispute resolution will occur, and that cant be totally managed by smart contracts, she says. 

In this sense, one may wonder whether DAOs are really a unique legal contraption at all, or whether they are to corporations roughly what registered civil partnerships are to marriage essentially the same thing with a modern lick of paint.

Heaver, in turn, argues that the concept of a traditional company is morally outdated. If the C-word is too dirty for a DAO team to associate with, a foundation may be another alternative.

Turnham sometimes guides teams to set up a foundation in the Cayman Islands, which can then act as the arms and legs of the DAO as a service provider with legal personality. While he acknowledges that the true Web3 crowd may consider such a solution as not meeting the threshold of a DAO due to its having a centralized legal entity, Turnham explains that the solution is not too far off the ideal because such a foundation can be effectively orphaned, with no need for shareholders.

MKR DAO dissolves Cayman Foundation in July to decentralize. ENS DAO forms one in November to have decentralization + manage legal. Crypto lawyers, discuss.

— ross (@z0r0zzz) November 4, 2021

Going back to corporations, there are also something he calls wrapped DAOs, which are incorporated in a jurisdiction such as his that allow for an anonymous or semi-anonymous board of directors to control the project in a way largely impossible within many other legal systems.

Legal risks

Nevertheless, the risks faced by foundation directors or even mere employees are significant because they cannot justify their actions simply by telling a judge that the community wanted me to do this if they were doing something obviously illegal (for a U.S. entity, at least) such as financial dealing with North Korea.

Turnham expands that this can be seen to support the view that DAOs should function much like corporations, with boards of directors that function essentially to give a sober second thought to community suggestions and avoid the super violent, super abusive or frankly super illegal activities that some DAO votes may try and push through. 

If the DAO you work for votes to become a crime syndicate, quit and send your tokens to a burn address
If the DAO you work for votes to become a crime syndicate, quit and send your tokens to a burn address. Source: Pexels

Such a corporate setup is at odds with genuine blockchain governance because governance tokenholders do not have executive authority to make day-to-day decisions, Turnham clarifies, describing them as more akin to adviser tokens for the DAO, which functions more like a community suggestion box for its administrators to consider. This model, he believes, is one that judges can easily understand.

When a DAO is not wrapped into a corporate shell, Turnham confirms that an entire project could be viewed as a general partnership. In effect, a judge could find that all tokenholders are in a common enterprise for profit as general partners, which comes with full liability for every other tokenholders actions concerning the project.

Thats a pretty violent outcome because guess what, you can now have 1,000 governance tokenholders that are now involved in a potential breach of securities laws securities regulators can theoretically go after every single one of them for being involved.

This undoubtedly sounds like a nightmare, and it is precisely why 400 years of corporate law were developed in the first place as a fence to protect investors. Painting in such broad historical strokes, the idea of using DAOs to circumvent the need for such legal entities comes across as a rather awkward venture at best and a doomed one at worst. 

Perhaps the answer lies in moderation. If a pure and traditional DAO proves unwieldy in most real-world applications, can the concept be watered down to meet reality? For Turnham, decentralization is a spectrum, and there is plenty of room between the black and white of cypherpunk ideals and traditional corporate structure. 

Paul agrees, noting that all the DAOs Ive looked at have had some level of centralization as a practical matter, they have found it hard to function without that.
Subscribe
The most engaging reads in blockchain. Delivered once a week.


    Subscribe to Magazine by Cointelegraph Newsletter.

    Securities law and governance tokens

    In addition to the risk of being found to be partnerships whose tokenholders are responsible for all manner of corporate actions, there is concern that the governance tokens issued by DAOs will be found to be securities in themselves. 

    If so, their issuance to the public falls under highly regulated securities legislation, especially in the U.S., where the sale of unregistered securities to unaccredited investors can be seen as a crime with severe fines and jail terms. Regulations vary around the world, so what may be of no legal concern in one jurisdiction may very much be a problem when tokens are received by someone in another country.

    DAO's were basically designed to cause headaches for legal professionals
    DAOs were basically designed to cause headaches for legal professionals. Source: Pexels

    Whether or not a token can be classified as a security in the United States is determined by the Howey Test, which defines that securities consist of (1) an investment of money (2) into a common enterprise with (3) a reasonable expectation of profit that is (4) derived from the efforts of others.

    Things dont look great at first glance people invest cryptocurrency to receive what appear to resemble voting shares in a business, usually with the hope of selling them for a higher amount.

    Arguments can of course be raised against any of the Howey Test points. For one, it could be argued that cryptocurrencies, such as ETH with which tokens are purchased, is not money, or that the tokens are distributed by other mechanisms, for example via airdrops to NFT holders, as in the case of APE tokens worth tens of thousands of dollars each to owners of Bored Ape Yacht Club NFTs. It can also be well argued that certain DAOs do not operate with the intent of generating profit, instead functioning as something more akin to a social club, gaming community or charity organization.

    There is virtually no case law in this area you are drafting into a vacuum.

    In Turnhams view, DAOs largely cannot be defined as securities because as decentralized organizations, they cannot necessarily be said to be managed by others though it is not clear if that would hold up in the courts. The Howey Test is not used by the Cayman and British Virgin Islands legal system, which he says is a favorable jurisdiction for DAOs to operate.

    When it comes time to distribute profits or excess capital, DAOs can spend surplus proceeds on buying tokens off the secondary market, thus creating a deflationary effect which is going to indirectly have some benefit and value to other tokenholders. In another example, a DAOs foundation can certainly agree to make a contractual payment to tokenholders on a pro-rata basis almost like a dividend, but technically not quite the same. This is important because otherwise, DAO tokens may begin to resemble bearer shares, stocks whose ownership is determined by physical possession of stock certificates rather than registered ownership, a form of security that is outlawed in the Cayman Islands.

    Turnham admits that there are few users of DAO tokens in the jurisdictions he works in, meaning that, in practice, those holding an interest in and participating in DAO governance are doing so from potentially more restrictive jurisdictions abroad. Before selling tokens, the correct legal advice, he says, is to advise teams to do the impossible:

    In a perfect world, I would say to DAO founders to go to every single jurisdiction and get a legal opinion from a lawyer from all those places to say whether your token is or isnt a security and whether you can or cannot sell it to people there.

    Getting 200 legal opinions on securities law is hardly affordable, so, in practice, diligent teams will seek legal clarity on higher risk jurisdictions, which Turnham figures include the U.S., U.K., Canada and Australia among others with special attention to any country that is expected to host a large number of tokenholders.

    Who knows a DAO that is alive and well and in public ?

    Most of what we label as DAOs are still in the phase of being fab crypto adjacent internet communities, far from decentralization. pic.twitter.com/R0H2XeSEIi

    — reka.eth (,) (@reka_eth) January 10, 2023

    A legitimate future?

    Despite the headaches DAOs are already producing for the legal profession, the lawyers interviewed for this article share a common thread of optimism regarding the new concept not just as a legal vehicle but as a movement for the modernization of the corporate world. 

    The key seems to be the way that DAOs encourage community, feedback and participation via online tools, such as Discord, something quite unlike normal public corporations, where once a year, you have an annual general meeting and the agenda gets rammed down investors throats without any real debate, says Turnham, likening it to a healthy and fundamental change in the way corporations have operated for generations.
    Related articles

    Sonic audit finds S token supply 48% above announced 3.175 billion

    Sonic audit finds S token supply 48% above announced 3.175 billion

    November 21, 2026
    HTX Research Publishes Six-Month Outlook for Bitcoin and Crypto Markets

    HTX Research Publishes Six-Month Outlook for Bitcoin and Crypto Markets

    November 20, 2026

    You couldnt have had a DAO 100 years ago, notes Paul, mentioning her observation that the movement has a positive energy that connects people around the world. In five years, she foresees DAOs in an increasingly cemented piece of organizational architecture:

    I think DAOs will keep growing theyll battle with regulation over the next few years, but I think they will come out of it.
    Read also
    Features

    Crypto critics: Can FUD ever be useful?

    Features

    Zooko’s Triangle: The Human-Readable Paradox at the Heart of Crypto Adoption

    Read Entire Article
    Tags: CointelegraphCryptocurrencyInvestmentMining Bitcoin
    Share76Tweet47

    Related Posts

    Sonic audit finds S token supply 48% above announced 3.175 billion

    Sonic audit finds S token supply 48% above announced 3.175 billion

    by Jon Hartney
    November 21, 2026
    0

    An independent audit found Sonic's S token supply is 470 billion, 48% above the 3175 billion announced at launch Sonic...

    HTX Research Publishes Six-Month Outlook for Bitcoin and Crypto Markets

    HTX Research Publishes Six-Month Outlook for Bitcoin and Crypto Markets

    by Jon Hartney
    November 20, 2026
    0

    Apia, Samoa, November 20, 2026 – HTX Research, the dedicated research arm of HTX, has published a new report titled...

    As traditional giants rush into digital dollars, USDD’s Yvonne Chia explains why 24/7 access, self-custody, and transparent yield give decentralized stablecoins an edge banks can’t replicate. 20 November – Road Town, Totorla, British Virgin Islands – Decentralized stablecoin protocol USDD is accelerating its multichain utility across TRON, Ethereum, and BNB Chain—combining automated sUSDD yield via its Smart Allocator with GasFree zero-TRX transfers—as traditional financial giants race to build competing stablecoin rails.  In a recent industry interview with instant exchange partner ChangeNOW, USDD Head of Communications Yvonne Chia outlined why self-custody, 24/7 settlement, and transparent onchain reserves give decentralized digital dollars a structural advantage over bank-issued alternatives. 1. Permissionless Access vs. Gatekept Accounts For billions of people globally, opening and maintaining a traditional bank account still involves paperwork, minimum balance requirements, geographic restrictions, and approval delays. Even when banks integrate stablecoin rails behind the scenes, those services remain gated behind legacy compliance walls and intermediary control. Crypto-native stablecoins flip that model on its head. As Yvonne Chia highlighted during the interview: “Compare this to a stablecoin like USDD, where all you need is a phone, a working internet connection, you can immediately start a wallet and you have access to your funds right away.” With USDD, users can access and manage their digital dollars directly through their own wallets, without depending on traditional financial intermediaries.  This represents a fundamental shift in financial access: users are no longer limited to the services, operating hours, or account structures of a single institution. Instead, they have the freedom to hold, manage, and transfer their assets on their own terms. Self-custody also gives users greater autonomy over their financial decisions. They can choose which wallets to use, where to transfer their assets, and which supported decentralized applications to interact with, without needing to route every transaction through a centralized financial institution.  With USDD, users’ digital dollars can move with them across an open blockchain ecosystem, rather than remaining tied to a particular bank or service provider. 2. 24/7 Global Settlement vs. “Banking Hours” Legacy payment networks still operate on decades-old schedules: weekend cutoffs, bank holidays, and multi-day cross-border settlement delays accompanied by hefty wire fees. Blockchain networks never close. Whether it is a Sunday night or a public holiday, USDD moves globally without depending on traditional banking operating hours or settlement windows. “We are able to have transfers 24/7 and we’re not limited to any traditional banking hours. So I think that in some ways, stablecoins are not just becoming banks, but exceeding what traditional banks can offer to users.” To make everyday transfers even smoother than fintech apps, USDD introduced GasFree integration on TRON, allowing users on supported wallets to pay network fees directly in USDD without needing to hold TRX. This removes another practical barrier to stablecoin adoption: having to acquire and maintain a separate gas token just to transfer digital dollars. With GasFree, eligible users can pay approximately 0.5 USDD per transaction, compared with around 1.5 USDT for a standard USDT transfer under the referenced fee conditions. These improvements matter because the usefulness of a stablecoin is not determined by its peg alone. Low-cost transfers, straightforward wallet experiences, and around-the-clock availability are what make digital dollars practical for everyday payments and global value transfers. 3. Passing Yield Back to Users vs. Bank Spreads Perhaps the sharpest contrast between banks and decentralized stablecoins lies in how yield is distributed.  In traditional banking, institutions take customer deposits, deploy them into yield-generating markets, and retain a significant portion of the returns. Everyday depositors may receive relatively low interest rates, while higher-yielding products often come with eligibility requirements, minimum deposits, or fixed maturity periods. Stablecoins introduce another way to participate in digital-dollar opportunities. Rather than keeping capital entirely within a traditional deposit account, users can access onchain yield opportunities through decentralized protocols and transparent investment mechanisms. USDD was built to return that value directly to holders. Through USDD Earn, users can deposit USDD to receive sUSDD, earning automated, competitive yield powered by our Smart Allocator system, with no fixed lock-up periods restricting access to their capital. For users, the distinction is important: USDD Earn provides access to a productive stablecoin while maintaining flexibility, rather than requiring users to commit their capital to a conventional fixed-term product. 4. Onchain Verification vs. Institutional Trust Traditional banks ask customers to trust closed-door balance sheets and periodic regulatory filings—until a crisis proves otherwise.  USDD takes a different approach through its “Don’t trust, verify” ethos, emphasizing publicly accessible onchain information and independent verification. Onchain Transparency: Smart contract addresses, collateral reserves, and Smart Allocator deployments are publicly viewable, allowing users to examine relevant information directly on the blockchain. Structured Disclosures: Quarterly Treasury Reports provide additional information about reserve positions, financial performance, and operational developments. Independent Security Reviews: USDD undergoes third-party security audits to assess its smart contracts and identify potential vulnerabilities. Transparency does not eliminate financial or technical risks, but it changes how users can evaluate them. Instead of relying exclusively on an institution’s assurances, users have access to information that can be independently examined and verified. 5. Beyond a Single Network: An Open, Multichain Financial Ecosystem Financial freedom is not just about holding digital dollars. It is also about being able to use them wherever opportunities and applications exist. A stablecoin confined to a single network or limited use case cannot fully realize the potential of open blockchain finance. Following its January 2025 protocol upgrade, USDD expanded natively from TRON onto Ethereum and BNB Chain, extending its reach across multiple blockchain ecosystems. This multichain presence allows USDD to connect with different communities, liquidity environments, and decentralized applications. Its sUSDD product has also expanded into DeFi integrations, including Pendle and Morpho, giving users additional ways to access yield strategies across supported ecosystems. The bigger picture is an interconnected financial ecosystem in which users can move between holding, transferring, exchanging, and deploying their stablecoins according to their own needs. These are not isolated functions. Together, they make stablecoins more useful as everyday financial infrastructure. The Future: Interconnected, Open, and Multichain Banks will undoubtedly continue using stablecoin rails to modernize their back-end settlement. However, true financial freedom comes from open networks where assets flow freely across protocols without intermediaries. For USDD, the opportunity goes beyond offering a dollar-pegged asset. It is about making digital dollars accessible, transferable, and productive across an interconnected financial ecosystem. From self-custody and 24/7 transfers to flexible yield opportunities and multichain DeFi access, these capabilities give users more ways to put their money to work. Banks may be bringing stablecoins into traditional finance. Crypto-native protocols are showing what stablecoins can make possible beyond it.

    As traditional giants rush into digital dollars, USDD’s Yvonne Chia explains why 24/7 access, self-custody, and transparent yield give decentralized stablecoins an edge banks can’t replicate. 20 November – Road Town, Totorla, British Virgin Islands – Decentralized stablecoin protocol USDD is accelerating its multichain utility across TRON, Ethereum, and BNB Chain—combining automated sUSDD yield via its Smart Allocator with GasFree zero-TRX transfers—as traditional financial giants race to build competing stablecoin rails. In a recent industry interview with instant exchange partner ChangeNOW, USDD Head of Communications Yvonne Chia outlined why self-custody, 24/7 settlement, and transparent onchain reserves give decentralized digital dollars a structural advantage over bank-issued alternatives. 1. Permissionless Access vs. Gatekept Accounts For billions of people globally, opening and maintaining a traditional bank account still involves paperwork, minimum balance requirements, geographic restrictions, and approval delays. Even when banks integrate stablecoin rails behind the scenes, those services remain gated behind legacy compliance walls and intermediary control. Crypto-native stablecoins flip that model on its head. As Yvonne Chia highlighted during the interview: “Compare this to a stablecoin like USDD, where all you need is a phone, a working internet connection, you can immediately start a wallet and you have access to your funds right away.” With USDD, users can access and manage their digital dollars directly through their own wallets, without depending on traditional financial intermediaries. This represents a fundamental shift in financial access: users are no longer limited to the services, operating hours, or account structures of a single institution. Instead, they have the freedom to hold, manage, and transfer their assets on their own terms. Self-custody also gives users greater autonomy over their financial decisions. They can choose which wallets to use, where to transfer their assets, and which supported decentralized applications to interact with, without needing to route every transaction through a centralized financial institution. With USDD, users’ digital dollars can move with them across an open blockchain ecosystem, rather than remaining tied to a particular bank or service provider. 2. 24/7 Global Settlement vs. “Banking Hours” Legacy payment networks still operate on decades-old schedules: weekend cutoffs, bank holidays, and multi-day cross-border settlement delays accompanied by hefty wire fees. Blockchain networks never close. Whether it is a Sunday night or a public holiday, USDD moves globally without depending on traditional banking operating hours or settlement windows. “We are able to have transfers 24/7 and we’re not limited to any traditional banking hours. So I think that in some ways, stablecoins are not just becoming banks, but exceeding what traditional banks can offer to users.” To make everyday transfers even smoother than fintech apps, USDD introduced GasFree integration on TRON, allowing users on supported wallets to pay network fees directly in USDD without needing to hold TRX. This removes another practical barrier to stablecoin adoption: having to acquire and maintain a separate gas token just to transfer digital dollars. With GasFree, eligible users can pay approximately 0.5 USDD per transaction, compared with around 1.5 USDT for a standard USDT transfer under the referenced fee conditions. These improvements matter because the usefulness of a stablecoin is not determined by its peg alone. Low-cost transfers, straightforward wallet experiences, and around-the-clock availability are what make digital dollars practical for everyday payments and global value transfers. 3. Passing Yield Back to Users vs. Bank Spreads Perhaps the sharpest contrast between banks and decentralized stablecoins lies in how yield is distributed. In traditional banking, institutions take customer deposits, deploy them into yield-generating markets, and retain a significant portion of the returns. Everyday depositors may receive relatively low interest rates, while higher-yielding products often come with eligibility requirements, minimum deposits, or fixed maturity periods. Stablecoins introduce another way to participate in digital-dollar opportunities. Rather than keeping capital entirely within a traditional deposit account, users can access onchain yield opportunities through decentralized protocols and transparent investment mechanisms. USDD was built to return that value directly to holders. Through USDD Earn, users can deposit USDD to receive sUSDD, earning automated, competitive yield powered by our Smart Allocator system, with no fixed lock-up periods restricting access to their capital. For users, the distinction is important: USDD Earn provides access to a productive stablecoin while maintaining flexibility, rather than requiring users to commit their capital to a conventional fixed-term product. 4. Onchain Verification vs. Institutional Trust Traditional banks ask customers to trust closed-door balance sheets and periodic regulatory filings—until a crisis proves otherwise. USDD takes a different approach through its “Don’t trust, verify” ethos, emphasizing publicly accessible onchain information and independent verification. Onchain Transparency: Smart contract addresses, collateral reserves, and Smart Allocator deployments are publicly viewable, allowing users to examine relevant information directly on the blockchain. Structured Disclosures: Quarterly Treasury Reports provide additional information about reserve positions, financial performance, and operational developments. Independent Security Reviews: USDD undergoes third-party security audits to assess its smart contracts and identify potential vulnerabilities. Transparency does not eliminate financial or technical risks, but it changes how users can evaluate them. Instead of relying exclusively on an institution’s assurances, users have access to information that can be independently examined and verified. 5. Beyond a Single Network: An Open, Multichain Financial Ecosystem Financial freedom is not just about holding digital dollars. It is also about being able to use them wherever opportunities and applications exist. A stablecoin confined to a single network or limited use case cannot fully realize the potential of open blockchain finance. Following its January 2025 protocol upgrade, USDD expanded natively from TRON onto Ethereum and BNB Chain, extending its reach across multiple blockchain ecosystems. This multichain presence allows USDD to connect with different communities, liquidity environments, and decentralized applications. Its sUSDD product has also expanded into DeFi integrations, including Pendle and Morpho, giving users additional ways to access yield strategies across supported ecosystems. The bigger picture is an interconnected financial ecosystem in which users can move between holding, transferring, exchanging, and deploying their stablecoins according to their own needs. These are not isolated functions. Together, they make stablecoins more useful as everyday financial infrastructure. The Future: Interconnected, Open, and Multichain Banks will undoubtedly continue using stablecoin rails to modernize their back-end settlement. However, true financial freedom comes from open networks where assets flow freely across protocols without intermediaries. For USDD, the opportunity goes beyond offering a dollar-pegged asset. It is about making digital dollars accessible, transferable, and productive across an interconnected financial ecosystem. From self-custody and 24/7 transfers to flexible yield opportunities and multichain DeFi access, these capabilities give users more ways to put their money to work. Banks may be bringing stablecoins into traditional finance. Crypto-native protocols are showing what stablecoins can make possible beyond it.

    by Jon Hartney
    November 20, 2026
    0

    As traditional giants rush into digital dollars, USDD’s Yvonne Chia explains why 24/7 access, self-custody, and transparent yield give decentralized...

    Banks Are Adopting Stablecoins: Here Is Why Crypto-Native Dollars Still Win on User Freedom

    Banks Are Adopting Stablecoins: Here Is Why Crypto-Native Dollars Still Win on User Freedom

    by Jon Hartney
    November 20, 2026
    0

    As traditional giants rush into digital dollars, USDD’s Yvonne Chia explains why 24/7 access, self-custody, and transparent yield give decentralized...

    IOSCO’s quantum warning names Ethereum and Solana, but not the network with the most exposed keys: bitcoin

    IOSCO’s quantum warning names Ethereum and Solana, but not the network with the most exposed keys: bitcoin

    by Jon Hartney
    November 20, 2026
    0

    IOSCO's 63-page quantum-risk report names Ethereum, Solana and Tron as examples and never mentions bitcoin, where an estimated 693 million...

    Load More
    • Trending
    • Comments
    • Latest
    Crypto, Fintech push back against banks’ war on open banking

    Crypto, Fintech push back against banks’ war on open banking

    October 21, 2025
    Bitcoin Cash (BCH) Pulls Back After Yesterday’s Big Push While Ecoterra Goes Up and Up

    Bitcoin Cash (BCH) Pulls Back After Yesterday’s Big Push While Ecoterra Goes Up and Up

    July 1, 2023
    Bitcoin ETFs shed $1.2B in red week, but Schwab remains bullish

    Bitcoin ETFs shed $1.2B in red week, but Schwab remains bullish

    October 18, 2025
    SUI Price Hits All-Time High – But Questions About Valuation Remain

    SUI Price Hits All-Time High – But Questions About Valuation Remain

    October 17, 2024
    All aboard! Elon Musk’s Vegas Loop now taking Dogecoin payments

    All aboard! Elon Musk’s Vegas Loop now taking Dogecoin payments

    0
    Crypto owners banned from working on US Government crypto policies

    Crypto owners banned from working on US Government crypto policies

    0
    Korean startup Uprise lost $20M shorting LUNC

    Korean startup Uprise lost $20M shorting LUNC

    0
    Ethereum testnet Merge mostly successful — ‘Hiccups will not delay the Merge.’

    Ethereum testnet Merge mostly successful — ‘Hiccups will not delay the Merge.’

    0
    Sonic audit finds S token supply 48% above announced 3.175 billion

    Sonic audit finds S token supply 48% above announced 3.175 billion

    November 21, 2026
    HTX Research Publishes Six-Month Outlook for Bitcoin and Crypto Markets

    HTX Research Publishes Six-Month Outlook for Bitcoin and Crypto Markets

    November 20, 2026
    Banks Are Adopting Stablecoins: Here Is Why Crypto-Native Dollars Still Win on User Freedom

    Banks Are Adopting Stablecoins: Here Is Why Crypto-Native Dollars Still Win on User Freedom

    November 20, 2026
    As traditional giants rush into digital dollars, USDD’s Yvonne Chia explains why 24/7 access, self-custody, and transparent yield give decentralized stablecoins an edge banks can’t replicate. 20 November – Road Town, Totorla, British Virgin Islands – Decentralized stablecoin protocol USDD is accelerating its multichain utility across TRON, Ethereum, and BNB Chain—combining automated sUSDD yield via its Smart Allocator with GasFree zero-TRX transfers—as traditional financial giants race to build competing stablecoin rails.  In a recent industry interview with instant exchange partner ChangeNOW, USDD Head of Communications Yvonne Chia outlined why self-custody, 24/7 settlement, and transparent onchain reserves give decentralized digital dollars a structural advantage over bank-issued alternatives. 1. Permissionless Access vs. Gatekept Accounts For billions of people globally, opening and maintaining a traditional bank account still involves paperwork, minimum balance requirements, geographic restrictions, and approval delays. Even when banks integrate stablecoin rails behind the scenes, those services remain gated behind legacy compliance walls and intermediary control. Crypto-native stablecoins flip that model on its head. As Yvonne Chia highlighted during the interview: “Compare this to a stablecoin like USDD, where all you need is a phone, a working internet connection, you can immediately start a wallet and you have access to your funds right away.” With USDD, users can access and manage their digital dollars directly through their own wallets, without depending on traditional financial intermediaries.  This represents a fundamental shift in financial access: users are no longer limited to the services, operating hours, or account structures of a single institution. Instead, they have the freedom to hold, manage, and transfer their assets on their own terms. Self-custody also gives users greater autonomy over their financial decisions. They can choose which wallets to use, where to transfer their assets, and which supported decentralized applications to interact with, without needing to route every transaction through a centralized financial institution.  With USDD, users’ digital dollars can move with them across an open blockchain ecosystem, rather than remaining tied to a particular bank or service provider. 2. 24/7 Global Settlement vs. “Banking Hours” Legacy payment networks still operate on decades-old schedules: weekend cutoffs, bank holidays, and multi-day cross-border settlement delays accompanied by hefty wire fees. Blockchain networks never close. Whether it is a Sunday night or a public holiday, USDD moves globally without depending on traditional banking operating hours or settlement windows. “We are able to have transfers 24/7 and we’re not limited to any traditional banking hours. So I think that in some ways, stablecoins are not just becoming banks, but exceeding what traditional banks can offer to users.” To make everyday transfers even smoother than fintech apps, USDD introduced GasFree integration on TRON, allowing users on supported wallets to pay network fees directly in USDD without needing to hold TRX. This removes another practical barrier to stablecoin adoption: having to acquire and maintain a separate gas token just to transfer digital dollars. With GasFree, eligible users can pay approximately 0.5 USDD per transaction, compared with around 1.5 USDT for a standard USDT transfer under the referenced fee conditions. These improvements matter because the usefulness of a stablecoin is not determined by its peg alone. Low-cost transfers, straightforward wallet experiences, and around-the-clock availability are what make digital dollars practical for everyday payments and global value transfers. 3. Passing Yield Back to Users vs. Bank Spreads Perhaps the sharpest contrast between banks and decentralized stablecoins lies in how yield is distributed.  In traditional banking, institutions take customer deposits, deploy them into yield-generating markets, and retain a significant portion of the returns. Everyday depositors may receive relatively low interest rates, while higher-yielding products often come with eligibility requirements, minimum deposits, or fixed maturity periods. Stablecoins introduce another way to participate in digital-dollar opportunities. Rather than keeping capital entirely within a traditional deposit account, users can access onchain yield opportunities through decentralized protocols and transparent investment mechanisms. USDD was built to return that value directly to holders. Through USDD Earn, users can deposit USDD to receive sUSDD, earning automated, competitive yield powered by our Smart Allocator system, with no fixed lock-up periods restricting access to their capital. For users, the distinction is important: USDD Earn provides access to a productive stablecoin while maintaining flexibility, rather than requiring users to commit their capital to a conventional fixed-term product. 4. Onchain Verification vs. Institutional Trust Traditional banks ask customers to trust closed-door balance sheets and periodic regulatory filings—until a crisis proves otherwise.  USDD takes a different approach through its “Don’t trust, verify” ethos, emphasizing publicly accessible onchain information and independent verification. Onchain Transparency: Smart contract addresses, collateral reserves, and Smart Allocator deployments are publicly viewable, allowing users to examine relevant information directly on the blockchain. Structured Disclosures: Quarterly Treasury Reports provide additional information about reserve positions, financial performance, and operational developments. Independent Security Reviews: USDD undergoes third-party security audits to assess its smart contracts and identify potential vulnerabilities. Transparency does not eliminate financial or technical risks, but it changes how users can evaluate them. Instead of relying exclusively on an institution’s assurances, users have access to information that can be independently examined and verified. 5. Beyond a Single Network: An Open, Multichain Financial Ecosystem Financial freedom is not just about holding digital dollars. It is also about being able to use them wherever opportunities and applications exist. A stablecoin confined to a single network or limited use case cannot fully realize the potential of open blockchain finance. Following its January 2025 protocol upgrade, USDD expanded natively from TRON onto Ethereum and BNB Chain, extending its reach across multiple blockchain ecosystems. This multichain presence allows USDD to connect with different communities, liquidity environments, and decentralized applications. Its sUSDD product has also expanded into DeFi integrations, including Pendle and Morpho, giving users additional ways to access yield strategies across supported ecosystems. The bigger picture is an interconnected financial ecosystem in which users can move between holding, transferring, exchanging, and deploying their stablecoins according to their own needs. These are not isolated functions. Together, they make stablecoins more useful as everyday financial infrastructure. The Future: Interconnected, Open, and Multichain Banks will undoubtedly continue using stablecoin rails to modernize their back-end settlement. However, true financial freedom comes from open networks where assets flow freely across protocols without intermediaries. For USDD, the opportunity goes beyond offering a dollar-pegged asset. It is about making digital dollars accessible, transferable, and productive across an interconnected financial ecosystem. From self-custody and 24/7 transfers to flexible yield opportunities and multichain DeFi access, these capabilities give users more ways to put their money to work. Banks may be bringing stablecoins into traditional finance. Crypto-native protocols are showing what stablecoins can make possible beyond it.


    As traditional giants rush into digital dollars, USDD’s Yvonne Chia explains why 24/7 access, self-custody, and transparent yield give decentralized stablecoins an edge banks can’t replicate. 20 November – Road Town, Totorla, British Virgin Islands – Decentralized stablecoin protocol USDD is accelerating its multichain utility across TRON, Ethereum, and BNB Chain—combining automated sUSDD yield via its Smart Allocator with GasFree zero-TRX transfers—as traditional financial giants race to build competing stablecoin rails. In a recent industry interview with instant exchange partner ChangeNOW, USDD Head of Communications Yvonne Chia outlined why self-custody, 24/7 settlement, and transparent onchain reserves give decentralized digital dollars a structural advantage over bank-issued alternatives. 1. Permissionless Access vs. Gatekept Accounts For billions of people globally, opening and maintaining a traditional bank account still involves paperwork, minimum balance requirements, geographic restrictions, and approval delays. Even when banks integrate stablecoin rails behind the scenes, those services remain gated behind legacy compliance walls and intermediary control. Crypto-native stablecoins flip that model on its head. As Yvonne Chia highlighted during the interview: “Compare this to a stablecoin like USDD, where all you need is a phone, a working internet connection, you can immediately start a wallet and you have access to your funds right away.” With USDD, users can access and manage their digital dollars directly through their own wallets, without depending on traditional financial intermediaries. This represents a fundamental shift in financial access: users are no longer limited to the services, operating hours, or account structures of a single institution. Instead, they have the freedom to hold, manage, and transfer their assets on their own terms. Self-custody also gives users greater autonomy over their financial decisions. They can choose which wallets to use, where to transfer their assets, and which supported decentralized applications to interact with, without needing to route every transaction through a centralized financial institution. With USDD, users’ digital dollars can move with them across an open blockchain ecosystem, rather than remaining tied to a particular bank or service provider. 2. 24/7 Global Settlement vs. “Banking Hours” Legacy payment networks still operate on decades-old schedules: weekend cutoffs, bank holidays, and multi-day cross-border settlement delays accompanied by hefty wire fees. Blockchain networks never close. Whether it is a Sunday night or a public holiday, USDD moves globally without depending on traditional banking operating hours or settlement windows. “We are able to have transfers 24/7 and we’re not limited to any traditional banking hours. So I think that in some ways, stablecoins are not just becoming banks, but exceeding what traditional banks can offer to users.” To make everyday transfers even smoother than fintech apps, USDD introduced GasFree integration on TRON, allowing users on supported wallets to pay network fees directly in USDD without needing to hold TRX. This removes another practical barrier to stablecoin adoption: having to acquire and maintain a separate gas token just to transfer digital dollars. With GasFree, eligible users can pay approximately 0.5 USDD per transaction, compared with around 1.5 USDT for a standard USDT transfer under the referenced fee conditions. These improvements matter because the usefulness of a stablecoin is not determined by its peg alone. Low-cost transfers, straightforward wallet experiences, and around-the-clock availability are what make digital dollars practical for everyday payments and global value transfers. 3. Passing Yield Back to Users vs. Bank Spreads Perhaps the sharpest contrast between banks and decentralized stablecoins lies in how yield is distributed. In traditional banking, institutions take customer deposits, deploy them into yield-generating markets, and retain a significant portion of the returns. Everyday depositors may receive relatively low interest rates, while higher-yielding products often come with eligibility requirements, minimum deposits, or fixed maturity periods. Stablecoins introduce another way to participate in digital-dollar opportunities. Rather than keeping capital entirely within a traditional deposit account, users can access onchain yield opportunities through decentralized protocols and transparent investment mechanisms. USDD was built to return that value directly to holders. Through USDD Earn, users can deposit USDD to receive sUSDD, earning automated, competitive yield powered by our Smart Allocator system, with no fixed lock-up periods restricting access to their capital. For users, the distinction is important: USDD Earn provides access to a productive stablecoin while maintaining flexibility, rather than requiring users to commit their capital to a conventional fixed-term product. 4. Onchain Verification vs. Institutional Trust Traditional banks ask customers to trust closed-door balance sheets and periodic regulatory filings—until a crisis proves otherwise. USDD takes a different approach through its “Don’t trust, verify” ethos, emphasizing publicly accessible onchain information and independent verification. Onchain Transparency: Smart contract addresses, collateral reserves, and Smart Allocator deployments are publicly viewable, allowing users to examine relevant information directly on the blockchain. Structured Disclosures: Quarterly Treasury Reports provide additional information about reserve positions, financial performance, and operational developments. Independent Security Reviews: USDD undergoes third-party security audits to assess its smart contracts and identify potential vulnerabilities. Transparency does not eliminate financial or technical risks, but it changes how users can evaluate them. Instead of relying exclusively on an institution’s assurances, users have access to information that can be independently examined and verified. 5. Beyond a Single Network: An Open, Multichain Financial Ecosystem Financial freedom is not just about holding digital dollars. It is also about being able to use them wherever opportunities and applications exist. A stablecoin confined to a single network or limited use case cannot fully realize the potential of open blockchain finance. Following its January 2025 protocol upgrade, USDD expanded natively from TRON onto Ethereum and BNB Chain, extending its reach across multiple blockchain ecosystems. This multichain presence allows USDD to connect with different communities, liquidity environments, and decentralized applications. Its sUSDD product has also expanded into DeFi integrations, including Pendle and Morpho, giving users additional ways to access yield strategies across supported ecosystems. The bigger picture is an interconnected financial ecosystem in which users can move between holding, transferring, exchanging, and deploying their stablecoins according to their own needs. These are not isolated functions. Together, they make stablecoins more useful as everyday financial infrastructure. The Future: Interconnected, Open, and Multichain Banks will undoubtedly continue using stablecoin rails to modernize their back-end settlement. However, true financial freedom comes from open networks where assets flow freely across protocols without intermediaries. For USDD, the opportunity goes beyond offering a dollar-pegged asset. It is about making digital dollars accessible, transferable, and productive across an interconnected financial ecosystem. From self-custody and 24/7 transfers to flexible yield opportunities and multichain DeFi access, these capabilities give users more ways to put their money to work. Banks may be bringing stablecoins into traditional finance. Crypto-native protocols are showing what stablecoins can make possible beyond it.

    November 20, 2026

    XBT.Market

    This website is an automated news feed powered by the Nebulome cloud system. The site is made possible by YYC TECH Consulting and Alberta Digital Mining Company. As a team with major crypto and bitcoin enthusiasm, we have curated major sources of news, trading and financial data to bring you, our viewer, an unbiased source of truth.

    Recent Posts

    • Sonic audit finds S token supply 48% above announced 3.175 billion November 21, 2026
    • HTX Research Publishes Six-Month Outlook for Bitcoin and Crypto Markets November 20, 2026
    • Banks Are Adopting Stablecoins: Here Is Why Crypto-Native Dollars Still Win on User Freedom November 20, 2026
    • As traditional giants rush into digital dollars, USDD’s Yvonne Chia explains why 24/7 access, self-custody, and transparent yield give decentralized stablecoins an edge banks can’t replicate. 20 November – Road Town, Totorla, British Virgin Islands – Decentralized stablecoin protocol USDD is accelerating its multichain utility across TRON, Ethereum, and BNB Chain—combining automated sUSDD yield via its Smart Allocator with GasFree zero-TRX transfers—as traditional financial giants race to build competing stablecoin rails. In a recent industry interview with instant exchange partner ChangeNOW, USDD Head of Communications Yvonne Chia outlined why self-custody, 24/7 settlement, and transparent onchain reserves give decentralized digital dollars a structural advantage over bank-issued alternatives. 1. Permissionless Access vs. Gatekept Accounts For billions of people globally, opening and maintaining a traditional bank account still involves paperwork, minimum balance requirements, geographic restrictions, and approval delays. Even when banks integrate stablecoin rails behind the scenes, those services remain gated behind legacy compliance walls and intermediary control. Crypto-native stablecoins flip that model on its head. As Yvonne Chia highlighted during the interview: “Compare this to a stablecoin like USDD, where all you need is a phone, a working internet connection, you can immediately start a wallet and you have access to your funds right away.” With USDD, users can access and manage their digital dollars directly through their own wallets, without depending on traditional financial intermediaries. This represents a fundamental shift in financial access: users are no longer limited to the services, operating hours, or account structures of a single institution. Instead, they have the freedom to hold, manage, and transfer their assets on their own terms. Self-custody also gives users greater autonomy over their financial decisions. They can choose which wallets to use, where to transfer their assets, and which supported decentralized applications to interact with, without needing to route every transaction through a centralized financial institution. With USDD, users’ digital dollars can move with them across an open blockchain ecosystem, rather than remaining tied to a particular bank or service provider. 2. 24/7 Global Settlement vs. “Banking Hours” Legacy payment networks still operate on decades-old schedules: weekend cutoffs, bank holidays, and multi-day cross-border settlement delays accompanied by hefty wire fees. Blockchain networks never close. Whether it is a Sunday night or a public holiday, USDD moves globally without depending on traditional banking operating hours or settlement windows. “We are able to have transfers 24/7 and we’re not limited to any traditional banking hours. So I think that in some ways, stablecoins are not just becoming banks, but exceeding what traditional banks can offer to users.” To make everyday transfers even smoother than fintech apps, USDD introduced GasFree integration on TRON, allowing users on supported wallets to pay network fees directly in USDD without needing to hold TRX. This removes another practical barrier to stablecoin adoption: having to acquire and maintain a separate gas token just to transfer digital dollars. With GasFree, eligible users can pay approximately 0.5 USDD per transaction, compared with around 1.5 USDT for a standard USDT transfer under the referenced fee conditions. These improvements matter because the usefulness of a stablecoin is not determined by its peg alone. Low-cost transfers, straightforward wallet experiences, and around-the-clock availability are what make digital dollars practical for everyday payments and global value transfers. 3. Passing Yield Back to Users vs. Bank Spreads Perhaps the sharpest contrast between banks and decentralized stablecoins lies in how yield is distributed. In traditional banking, institutions take customer deposits, deploy them into yield-generating markets, and retain a significant portion of the returns. Everyday depositors may receive relatively low interest rates, while higher-yielding products often come with eligibility requirements, minimum deposits, or fixed maturity periods. Stablecoins introduce another way to participate in digital-dollar opportunities. Rather than keeping capital entirely within a traditional deposit account, users can access onchain yield opportunities through decentralized protocols and transparent investment mechanisms. USDD was built to return that value directly to holders. Through USDD Earn, users can deposit USDD to receive sUSDD, earning automated, competitive yield powered by our Smart Allocator system, with no fixed lock-up periods restricting access to their capital. For users, the distinction is important: USDD Earn provides access to a productive stablecoin while maintaining flexibility, rather than requiring users to commit their capital to a conventional fixed-term product. 4. Onchain Verification vs. Institutional Trust Traditional banks ask customers to trust closed-door balance sheets and periodic regulatory filings—until a crisis proves otherwise. USDD takes a different approach through its “Don’t trust, verify” ethos, emphasizing publicly accessible onchain information and independent verification. Onchain Transparency: Smart contract addresses, collateral reserves, and Smart Allocator deployments are publicly viewable, allowing users to examine relevant information directly on the blockchain. Structured Disclosures: Quarterly Treasury Reports provide additional information about reserve positions, financial performance, and operational developments. Independent Security Reviews: USDD undergoes third-party security audits to assess its smart contracts and identify potential vulnerabilities. Transparency does not eliminate financial or technical risks, but it changes how users can evaluate them. Instead of relying exclusively on an institution’s assurances, users have access to information that can be independently examined and verified. 5. Beyond a Single Network: An Open, Multichain Financial Ecosystem Financial freedom is not just about holding digital dollars. It is also about being able to use them wherever opportunities and applications exist. A stablecoin confined to a single network or limited use case cannot fully realize the potential of open blockchain finance. Following its January 2025 protocol upgrade, USDD expanded natively from TRON onto Ethereum and BNB Chain, extending its reach across multiple blockchain ecosystems. This multichain presence allows USDD to connect with different communities, liquidity environments, and decentralized applications. Its sUSDD product has also expanded into DeFi integrations, including Pendle and Morpho, giving users additional ways to access yield strategies across supported ecosystems. The bigger picture is an interconnected financial ecosystem in which users can move between holding, transferring, exchanging, and deploying their stablecoins according to their own needs. These are not isolated functions. Together, they make stablecoins more useful as everyday financial infrastructure. The Future: Interconnected, Open, and Multichain Banks will undoubtedly continue using stablecoin rails to modernize their back-end settlement. However, true financial freedom comes from open networks where assets flow freely across protocols without intermediaries. For USDD, the opportunity goes beyond offering a dollar-pegged asset. It is about making digital dollars accessible, transferable, and productive across an interconnected financial ecosystem. From self-custody and 24/7 transfers to flexible yield opportunities and multichain DeFi access, these capabilities give users more ways to put their money to work. Banks may be bringing stablecoins into traditional finance. Crypto-native protocols are showing what stablecoins can make possible beyond it. November 20, 2026
    • IOSCO’s quantum warning names Ethereum and Solana, but not the network with the most exposed keys: bitcoin November 20, 2026

    News Categories

    • Bitcoin
    • Blockchain
    • Business
    • Market
    • Uncategorized

    Tags

    bitcoinMagzine Cointelegraph Cryptocurrency insidebitcoins Investment Mining Bitcoin NewsBTC

    Quicklinks

    • Home
    • Coins MarketCap
    • Crypto Exchanges
    • Crypto Calculator
    • Top Gainers and Loser
    • News
    • Contact Us

    © 2022 Xbt.Market - Powered by YYC Tech Consulting & ADMCO.

    No Result
    View All Result
    • Home
    • Coins MarketCap
    • Crypto Exchanges
    • Crypto Calculator
    • Top Gainers and Loser
    • News
    • Contact Us

    © 2022 Xbt.Market by Nebulome.

    • Steakhouse EURCV Morpho VaultSteakhouse EURCV Morpho Vault(STEAKEURCV)$0.000000-100.00%
    • FibSwap DEXFibSwap DEX(FIBO)$0.0084659.90%
    • TruFin Staked APTTruFin Staked APT(TRUAPT)$8.020.00%
    • bitcoinBitcoin(BTC)$84,372.003.58%
    • ethereumEthereum(ETH)$1,885.365.68%
    • tetherTether(USDT)$1.000.00%
    • rippleXRP(XRP)$2.186.84%
    • USDEXUSDEX(USDEX)$1.07-0.53%
    • binancecoinBNB(BNB)$617.995.03%
    • Wrapped SOLWrapped SOL(SOL)$143.66-2.32%
    • solanaSolana(SOL)$128.974.23%
    • usd-coinUSDC(USDC)$1.000.01%
    • dogecoinDogecoin(DOGE)$0.1736117.78%
    • cardanoCardano(ADA)$0.687.61%
    • tronTRON(TRX)$0.2342340.79%
    • staked-etherLido Staked Ether(STETH)$1,884.065.48%
    • Gaj FinanceGaj Finance(GAJ)$0.0059271.46%
    • Content BitcoinContent Bitcoin(CTB)$24.482.55%
    • USD OneUSD One(USD1)$1.000.11%
    • wrapped-bitcoinWrapped Bitcoin(WBTC)$84,309.003.84%
    • ToncoinToncoin(TON)$4.157.66%
    • UGOLD Inc.UGOLD Inc.(UGOLD)$3,042.460.08%
    • ParkcoinParkcoin(KPK)$1.101.76%
    • chainlinkChainlink(LINK)$14.027.76%
    • leo-tokenLEO Token(LEO)$9.211.17%
    • stellarStellar(XLM)$0.2743585.70%
    • avalanche-2Avalanche(AVAX)$19.647.71%
    • Wrapped stETHWrapped stETH(WSTETH)$2,256.395.40%
    • USDSUSDS(USDS)$1.00-0.01%
    • SuiSui(SUI)$2.429.03%
    • shiba-inuShiba Inu(SHIB)$0.0000137.71%
    • hedera-hashgraphHedera(HBAR)$0.17284810.00%
    • Yay StakeStone EtherYay StakeStone Ether(YAYSTONE)$2,671.07-2.84%
    • polkadotPolkadot(DOT)$4.257.34%
    • litecoinLitecoin(LTC)$85.265.04%
    • bitcoin-cashBitcoin Cash(BCH)$314.248.23%
    • mantra-daoMANTRA(OM)$6.301.94%
    • Pundi AIFXPundi AIFX(PUNDIAI)$16.000.00%
    • PengPeng(PENG)$0.60-13.59%
    • Bitget TokenBitget Token(BGB)$4.664.95%
    • wethWETH(WETH)$1,884.285.66%
    • Ethena USDeEthena USDe(USDE)$1.00-0.04%
    • Binance Bridged USDT (BNB Smart Chain)Binance Bridged USDT (BNB Smart Chain)(BSC-USD)$1.00-0.18%
    • MurasakiMurasaki(MURA)$4.23-13.71%
    • Black PhoenixBlack Phoenix(BPX)$3.351,000.00%
    • Pi NetworkPi Network(PI)$0.714.53%
    • HyperliquidHyperliquid(HYPE)$13.729.80%
    • Wrapped eETHWrapped eETH(WEETH)$2,003.675.53%
    • WhiteBIT CoinWhiteBIT Coin(WBT)$28.350.76%
    • moneroMonero(XMR)$217.841.31%
    • Zypto TokenZypto Token(ZYPTO)$0.037139-3.47%
    • uniswapUniswap(UNI)$6.217.66%
    • AptosAptos(APT)$5.395.79%
    • PepePepe(PEPE)$0.00000811.37%
    • daiDai(DAI)$1.00-0.01%
    • nearNEAR Protocol(NEAR)$2.635.26%
    • XT.comXT.com(XT)$3.08-1.65%
    • Layer One XLayer One X(L1X)$23.35454.66%
    • sUSDSsUSDS(SUSDS)$1.050.05%
    • okbOKB(OKB)$48.762.12%
    • gatechain-tokenGate(GT)$22.883.58%
    • crypto-com-chainCronos(CRO)$0.1015853.46%
    • Coinbase Wrapped BTCCoinbase Wrapped BTC(CBBTC)$84,342.003.68%
    • MantleMantle(MNT)$0.814.44%
    • Tokenize XchangeTokenize Xchange(TKX)$33.460.86%
    • internet-computerInternet Computer(ICP)$5.517.85%
    • ethereum-classicEthereum Classic(ETC)$17.074.81%
    • OndoOndo(ONDO)$0.817.47%
    • First Digital USDFirst Digital USD(FDUSD)$1.00-0.12%
    • aaveAave(AAVE)$168.6110.19%
    • Aerarium FiAerarium Fi(AERA)$7.14-13.11%
    • Ethena Staked USDeEthena Staked USDe(SUSDE)$1.170.30%
    • BSCEXBSCEX(BSCX)$237.310.49%
    • Official TrumpOfficial Trump(TRUMP)$10.354.36%
    • vechainVeChain(VET)$0.0233636.04%
    • cosmosCosmos Hub(ATOM)$4.538.09%
    • fantomFantom(FTM)$0.70-1.56%
    • BittensorBittensor(TAO)$231.277.72%
    • BlackRock USD Institutional Digital Liquidity FundBlackRock USD Institutional Digital Liquidity Fund(BUIDL)$1.000.00%
    • EthenaEthena(ENA)$0.3616194.37%
    • render-tokenRender(RENDER)$3.6710.91%
    • filecoinFilecoin(FIL)$2.927.72%
    • CelestiaCelestia(TIA)$3.181.75%
    • Black AgnusBlack Agnus(FTW)$0.000183423.46%
    • Lombard Staked BTCLombard Staked BTC(LBTC)$84,465.004.02%
    • POL (ex-MATIC)POL (ex-MATIC)(POL)$0.2063993.13%
    • KaspaKaspa(KAS)$0.0682239.38%
    • STAUSTAU(STAU)$0.17397910.95%
    • FasttokenFasttoken(FTN)$4.020.01%
    • Sonic (prev. FTM)Sonic (prev. FTM)(S)$0.5212.98%
    • algorandAlgorand(ALGO)$0.1896979.65%
    • ORA CoinORA Coin(ORA)$4.885.92%
    • ArbitrumArbitrum(ARB)$0.3397526.22%
    • Arbitrum Bridged USDT (Arbitrum)Arbitrum Bridged USDT (Arbitrum)(USDT)$1.000.07%
    • GGTKNGGTKN(GGTKN)$0.1121180.75%
    • kucoin-sharesKuCoin(KCS)$11.231.19%
    • Solv Protocol SolvBTCSolv Protocol SolvBTC(SOLVBTC)$84,076.003.32%
    • fetch-aiArtificial Superintelligence Alliance(FET)$0.4856098.68%
    • optimismOptimism(OP)$0.776.43%
    • StoryStory(IP)$4.75-2.68%